TechBio
Making the advantage count

 Forewords
Dr Emma Lawrence
Head of Data Tech Policy and Public Affairs, BIA
In 2021 the BIA published its first report on what we then called “tech bio”. In it and the following reports we repeatedly highlighted the absence of a clear route to health data in the UK. Five years on, that place is being built. The Health Data Research Service (HDRS), backed by up to £600 million from Government and Wellcome, is the answer to a request this sector has been making for as long as it has had a name. It isn’t the same as success.
A front door only matters if companies can afford to walk through it. Our health data vision, published in May, found SMEs paying anywhere from £9,000 a year to many times that for access to UK datasets. At the top of that range, the companies most likely to build something new here are the least able to pay. How HDRS prices access, and who it serves first, will decide whether UK health data becomes an advantage for UK companies or those with the deepest pockets.
We believe that UK companies should have the earliest and easiest access to these and other national health assets. This will give them a home advantage through which they can develop, to scale and serve the world from here.
The money tells a similar story. Last year’s report showed a sector that is good at starting companies and poor at growing them: 74 seed rounds between 2020 and 2024, and only five at Series B or later. This year brought the biggest raise we have recorded, Isomorphic Labs’ $2.1 billion Series B, and the biggest exit, Amgen’s purchase of Oxford’s Dark Blue Therapeutics. The data tells a story of the haves and have-nots: UK potential that needs capital to match.
This year’s report is shorter than the last two. We have not repeated the full financing analysis, because the picture has not moved enough in a year. Instead, we have picked out the deals that mattered, asked an investor what they look for now, and looked at where TechBio is starting to meet engineering biology.
A big thank you to all our contributors and our sponsors CWG and Kadans, without whom this report could not happen. I look forward to seeing you all at our TechBio UK conference on 13 October.
Mairi Dillon
Associate Director, Science Ecosystem, CWG
A TechBio company is only as fast as the distance between its model, its experiment and its real-world user. That distance is not only physical. It is the time it takes to reach and validate the data, find a laboratory, put a question to a regulator or get an investor into the room. This report describes a sector that is good at generating ideas and starting companies yet struggles to grow them. The funding gap is real, but beneath it sits a distance gap, and a distance gap is something a place can close.
TechBio is not just biotechnology with software added. A model proposes, an experiment tests, the results feed back and the cycle begins again. A conventional biotech can organise itself around one modality or discipline and one long timeline. A TechBio company has to run several at once, and its advantage lies in how quickly it can turn that loop. Each turn draws on a different neighbour: data, power, compute, work in the lab or office, regulators, capital, talent, collaborators and, importantly, patients. In most places, those neighbours are scattered across a city or a country. In Canary Wharf, they are within a 15-minute walk.
The UK’s advantage in TechBio is that so many of the pieces already exist. Some of what this report calls for requires policy, such as improved data access and later-stage capital, and we welcome the momentum from initiatives like HDRS and the Mansion House reforms. However, closing the distance gap doesn’t always need policy. It needs places designed around how TechBio actually works, and built with the sector rather than for it. One North Quay aspires to do this. That is how we make the advantage count for the UK’s international competitiveness: bring the key components together, back moonshot thinking and double down on connectivity.
 The big picture for TechBio
The big picture: an advantage not yet cashed in
A year ago we wrote that UK TechBio had grown from promise to presence. That still holds. What has changed is how uneven it looks.
In the last year we’ve seen the UK business environment become more attractive for life science companies. Median clinical trial set–up times fell from 169 to 122 days, and the NICE threshold rose for the first time since 1999. However, as the strategic importance of AI, data and genomics increases globally, we are seeing modern forms of protectionism through data localisation mandates, digital sovereignty requirements, technology export controls and restrictions on cross-border data flows. In June, for example, the US Government briefly cut external access to two of Anthropic’s AI models, until the controls were lifted at the end of the month.
Start with what the UK has. The Health Data Research Service (HDRS) now has a growing team, a home and a job to do: give companies one route into national-scale health data. Around it sit UK Biobank, Our Future Health, Genomics England and a research base that keeps producing companies. No other country has quite this longitudinal mix of multi-modal and truly diverse data.
But it isn’t the only country trying. More than 200 large patient datasets worldwide already link healthcare records with genomic data, and the BIA’s health data vision argues that size alone will no longer decide where companies go. They will look at how quickly and predictably they can get access, how good the multiomic and longitudinal data is, whether consented patients can be recontacted for trials, and how clear the rules are. On several of those, the UK is still catching up.
The competition isn’t only about patient data. On 7 October, Biohub, the research organisation backed by Mark Zuckerberg and Priscilla Chan, announced $1.8 billion for its Virtual Biology Initiative, an open collection of biological data built for AI. The US Department of Energy and the NIH are each contributing more than $500 million, much of it in kind, and Google DeepMind, Meta and London-based Isomorphic Labs are adding $300 million between them. Data on that scale, given away free, raises a fair question: will curated cohorts like UK Biobank and Our Future Health still matter? We think they will. Open lab data can show how cells behave. It can’t tell you what happened to half a million people followed for nearly two decades, as UK Biobank can. The harder question is how the UK lets AI learn from those cohorts without the value being carried off elsewhere.
Price is the one that bites first for small companies. Sub-national genomic and clinical datasets are available to SMEs for £9,000 to £40,000 a year, while access to Our Future Health can outstrip that. For a seed-stage company, that difference decides whether the UK’s best dataset is part of the plan at all.
Then there’s the money. In our data, UK TechBio companies raised around £1.9 billion in disclosed venture funding between October 2025 and September 2026. Isomorphic Labs’ Series B accounts for more than 80% of it. Take that single round away and the rest of the sector raised around £315 million between them. A year ago we pointed to the gap between plentiful seed rounds and scarce later ones. This year the gap looks, if anything, wider. It’s just hidden behind one very large number.
That isn’t the whole story. Some of the UK’s strongest TechBio companies are now raising at a scale that was rare five years ago. Basecamp Research, which builds AI models of biology from its own genomic data, raised $140 million in September. IMU Biosciences, which uses machine learning to profile the immune system from a blood sample, took its Series A to more than $53 million in June, and in September signed a licensing partnership with Eurofins Transplant Genomics. Relation Therapeutics extended its seed round in December and signed two major pharma partnerships within a year. Look at who led those rounds, though, and last year’s pattern holds. IMU’s was co-led by two UK investors, IQ Capital and Molten Ventures, with £5 million from the British Business Bank. Basecamp’s was led by S32, a Californian fund, and much of Relation’s new money came from overseas. The bigger the round, the further from home the lead investor tends to be.
The year’s two biggest outcomes show both sides of the UK position. Isomorphic’s round drew in Sovereign AI, the UK’s own fund, alongside some of the largest investors in the world. Dark Blue Therapeutics, an Oxford cancer company, was bought by Amgen for a reported $840 million: more than Exscientia’s £490 million sale, which we called the sector’s largest exit only last year. Selling well is a good result for founders and investors. Whether it’s a good result for the UK depends on what stays behind.
Kate Bingham put it plainly in her foreword to the health data vision: “Too often, the value created by UK science is captured elsewhere.” We agree, and we don’t think it’s inevitable.
Too often, the value created by UK science is captured elsewhere.
Kate Bingham
SV Health Investors
Making the advantage count means a handful of unglamorous things. Data has to be priced so that UK companies can afford it. Later-stage money needs to be available here, so that the Series B conversation doesn’t start with a flight to Boston. And growing companies need the right talent pool to tap into. None of this is new. What’s new is that, with HDRS, one of the pieces the sector asked for is finally in place. The next year will show whether the rest follows.
A view from CWG
From validation to scale: it takes an ecosystem
Mairi Dillon
Associate Director, Science Ecosystem, CWG
In the recent TechBio market, there has been a noticeable shift in appetite away from pure AI drug discovery platforms and towards the application of models within the operational and clinical phases of biotechnology. To mature, the market now needs these new business models to prove themselves by successfully and safely navigating clinical development. We know that achieving this scale and throughput requires multiple inputs and multiple neighbours.
TechBio companies tell us they want room to expand without relocating, and they want quality talent, clinical expertise, investors, technology partners and regulators within easy reach. Our response has been to bring the whole chain together, and with One North Quay on the horizon, we continue to build our ecosystem to curate the right environment. More than 40 life sciences and healthcare organisations are now based here. We’re home to UK data assets such as Genomics England, CPRD, NHS Transformation and Barts Life Sciences, as well as a strong, multidisciplinary tech talent pool. Alongside our wider commercial community, we have more than 180 start-ups at our Level39 incubator, bringing together experts in AI, cybersecurity and digital engineering, the infrastructure TechBio runs on. Canary Wharf grew up as a global financial district, so investors, banks and advisers are embedded too. High-growth companies such as IMU Biosciences, which pairs AI and deep immune profiling to take a precision approach to the human immune system, and Touchlight, which uses a cell-free enzymatic platform to manufacture high-purity synthetic DNA, have both set up at the London Innovation Centre, choosing to join this community.
Regulation is part of the chain too, and One North Quay is a few minutes’ walk from the MHRA’s headquarters. In October the Government accepted in full the 44 recommendations of the national commission on regulating AI in healthcare, drawn from the views of more than 12,000 patients, clinicians and members of the public. The MHRA will now turn them into a working regulatory framework, and has already opened the third phase of its AI Airlock. For companies building AI into healthcare, the people writing the rules are close by and keen to engage with industry.
This is connectivity in two senses. In the data sense, the organisations that hold, govern and analyse health data sit alongside the companies that need them, so questions of access, standards and assurance can be raised early and in person. In the human sense, a founder can be in the laboratory in the morning, with a regulator at lunch and in front of investors in the afternoon. Neither replaces good policy. Both make good policy easier to use.
One North Quay is where this thinking becomes physical. Due to complete in 2028, it is set to become London’s most powerfully connected campus and Europe’s largest purpose-built commercial science, innovation and tech facility. It is a vertical campus with ample amenity space throughout, designed so that a company can start small and grow within it without leaving the community around it.
In recent discussions, TechBio founders described the challenges they face around data provenance and linkage, and the time they spend translating between technology and biology, and between animal models and human physiology. They still look to the US for capital beyond initial pre-seed and seed rounds. None of this is simple, but it has to be worked through if TechBio is to realise its world-changing potential.
A connected environment can help ease these challenges and shorten the distance between discovery and impact. If the last few years proved that TechBio works, the next few will determine where it grows. We want the answer to be Canary Wharf.
 The year’s big deals
We haven’t repeated our full financing analysis this year. But here are six deals from the past twelve months that say something about where UK TechBio stands. They’re chosen for what they show, not only for their size.

Isomorphic Labs: $2.1 billion Series B (May 2026)
The London-based Alphabet company raised $2.1 billion in a round led by Thrive Capital, with GV, MGX, CapitalG, Temasek Trust Capital, Alphabet and the UK’s Sovereign AI fund taking part. The money will fund its AI drug design engine, global expansion and its own pipeline of drug candidates. That last point matters. Isomorphic is no longer only a platform selling to pharma, and investors are paying for the medicines as well as the models.
Dark Blue Therapeutics: acquired by Amgen (January 2026)
Amgen bought the Oxford-based cancer company for a reported $840 million, making it the largest exit in our data. Dark Blue leverages functional genomics and proprietary data to identify both druggable mechanisms and biomarkers to identify patients. It’s a strong return for its backers and another UK company whose next chapter will be written by an overseas owner.
Chemify: Series B extended, plus £22 million in public funding (October 2025 and September 2026)
The Glasgow company, which automates the design and making of new molecules, raised a Series B led by Insight Partners and Wing Venture Capital in October 2025. It has since extended the round to £51.9 million. In September, Scottish Enterprise and the UK Government committed £22 million to support its growth and up to 300 jobs. Chemify is funding the remaining £67.9 million of the £89.9 million project, which will take its Scottish workforce from 152 to around 450 and include a new global headquarters in Govan. It’s a clear example of public money being used to keep a scaling company here.
Infinitopes: $35 million seed (January 2026)
The Oxford company is developing a cancer vaccine designed to stop oesophageal cancer returning after surgery. Its seed round, co-led by Octopus Ventures and Amplify Partners, was the largest in our data. It stands out for its backers too: Cancer Research Horizons, Macmillan Cancer Support and the CRIS Cancer Foundation all invested alongside venture firms.
Qureight: $20 million Series B (July 2026)
Cambridge-based Qureight uses AI to organise and analyse imaging and clinical data in complex lung diseases. Molten Ventures led the round, which will fund an in-house AI imaging lab and expansion into asthma, lung cancer, pulmonary hypertension, bronchiectasis and drug-induced lung toxicity. A reminder that TechBio isn’t only about drug discovery.
Antiverse: $9.3 million Series A (January 2026)
The Cardiff company uses machine learning to predict how antibodies bind to difficult drug targets. Its Series A, led by Soulmates Ventures, drew on Welsh investors including the Development Bank of Wales and Cardiff Capital Region. Most UK TechBio money still goes to London, Oxford and Cambridge. Antiverse shows it doesn’t have to.
Pharma partnerships
Money raised is one measure. For many TechBio companies, the deal that matters most is a partnership with a major drug company: proof that the platform works on someone else’s problem, usually with cash up front. These deals rarely appear in funding tables, but the past year brought several.
Relation Therapeutics and Novartis (December 2025)
A multi-programme collaboration to find new targets for atopic diseases such as eczema. Relation receives $55 million in upfront payment, equity and research funding, and is eligible for up to $1.7 billion in milestones, plus royalties.
Relation Therapeutics and GSK (July 2026)
A $110 million collaboration to generate large-scale human cellular data and use it to train AI foundation models for drug discovery. It builds on the two companies’ earlier partnerships in fibrosis and osteoarthritis.
LabGenius and Sanofi (December 2025)
LabGenius’s second deal with Sanofi applies its machine learning platform to improve Sanofi’s Nanobody molecules against new inflammation targets.
LabGenius and LG Chem (June 2026)
A research and licence option agreement to design multispecific antibodies for cancer, with an upfront payment and research funding from LG Chem.
Between them, Relation’s two deals carry more than $1.8 billion in potential value. As Diana Roettger of LifeArc Ventures argues in our investor view, a partnership is strong validation, though not the same as proof that a platform makes better medicines.
Not every story was about growth. BenevolentAI, once one of the best-known listed names in UK TechBio, was taken private in March 2025.
About the data
Deal information in this report comes from PitchBook and covers disclosed transactions between October 2025 and September 2026 involving UK companies on the BIA’s list of TechBio companies. Figures are as reported and converted to sterling by PitchBook; undisclosed deals are not included, and acquisition values may be estimates. The list of companies was compiled by the BIA using our definition of TechBio: companies that make significant use of AI, machine learning or modern computational and modelling approaches in their core work. Basecamp Research and IMU Biosciences have been added to the list this year. Pharma partnerships are drawn from Beauhurst news coverage and company announcements, because PitchBook records deals only where money changes hands. The deals featured were chosen to illustrate the report’s themes and are not a ranking.
 UK companies driving innovation
Spotlight: where TechBio meets engineering biology
For most of its short life, TechBio has meant software: models that predict protein structures, rank drug targets or read scans. The companies drawing attention now are doing something harder. They’re joining computation to physical biology and chemistry, and they’re building the lab and the model together.
Chemify is the clearest example in this year’s deals. It writes chemistry as code and runs it on automated equipment. Its first Chemifarm, an automated facility for designing and making molecules, opened in Glasgow in 2025, and its public funding will help build a second-generation version. The model is only as good as the experiments it can run, so the company is investing in both.
Basecamp Research, whose chief executive Glen Gowers speaks at TechBio UK, has taken a similar bet from the data side. It has built the Trillion Gene Atlas, a very large genomics database, and a family of biology foundation models called EDEN, which feed a pipeline of programmable therapeutics.
At the earliest stage, Hijack Bio (see case studies) is engineering gut bacteria to make medicines inside the body. There, computational design and synthetic biology are the same project.
For the UK, this is where the advantage could count most, and it’s also where the costs of growing are highest. A software company can scale on cloud credits. A company running automated chemistry or engineering living cells needs labs, equipment, specialist staff and patient money. Every one of those is harder to find here at Series B than at seed.
These questions will be picked up at TechBio UK on 13 October, where companies in the engineering biology track will show what building the lab and the model together looks like in practice.
TechBio showcase
These three companies are presenting in the innovation showcase at TechBio UK.
Case study
Scripta Therapeutics: flipping the script on drug discovery
Much of drug discovery goes after a set of well-studied targets, biased by what has gone before, leaving much of disease biology unexplored.
Scripta Therapeutics takes a different approach. Its platform builds unbiased maps of biology from patient data, discovering critical nodes that play a central role in driving disease. The nodes are proteins called transcription factors, masters of a powerful regulatory layer of biology that dictates which genes a cell switches on or off.
Transcription factors have long been seen as intractable for drug discovery, but Scripta’s TechBio platform unlocks their potential. Its computer vision AI system detects functional defects in the regulatory layer and identifies novel chemistry that can reverse them.
In disease models developed with Professor Noel Buckley at the University of Oxford, these compounds restore a healthy cellular profile by reversing mechanistic drivers of disease, rather than just dealing with the downstream effects.
Scripta was founded by Dr Peter Hamley, an experienced biotech and pharma drug discoverer, and emerged from stealth with a $12 million seed round co-led by Oxford Science Enterprises and Apollo Health Ventures.
While Scripta is focusing first on Alzheimer’s disease and ALS, they find that defects in the regulatory layer of biology underpin many diseases. Its integrated TechBio approach flips the script on how we think about halting or even reversing complex diseases.
“For us, TechBio means the ability to do drug discovery on a different scale. AI lets us read the regulatory layer of patient cells and identify modulators of this regulation using computer vision. Our scientists then take this information and transform it into new therapeutics. That partnership is how we can make better medicines.”
Dr Peter Hamley, CEO, Scripta Therapeutics
Case study
Cyclana Bio: learning from a sample nobody was collecting
Endometriosis affects around one in ten women, yet it remains poorly understood, and current treatments rarely tackle its underlying causes. Cambridge-based Cyclana Bio thinks part of the problem is where researchers have been looking.
Its answer is menstrual fluid, a sample that arrives every month without a biopsy. Donations from an ongoing observational clinical study are used to recreate working disease tissue in the lab. Alongside that, the company is collecting multi-omic data from biopsies and clinical data to build what it describes as the first tissue-level disease database.
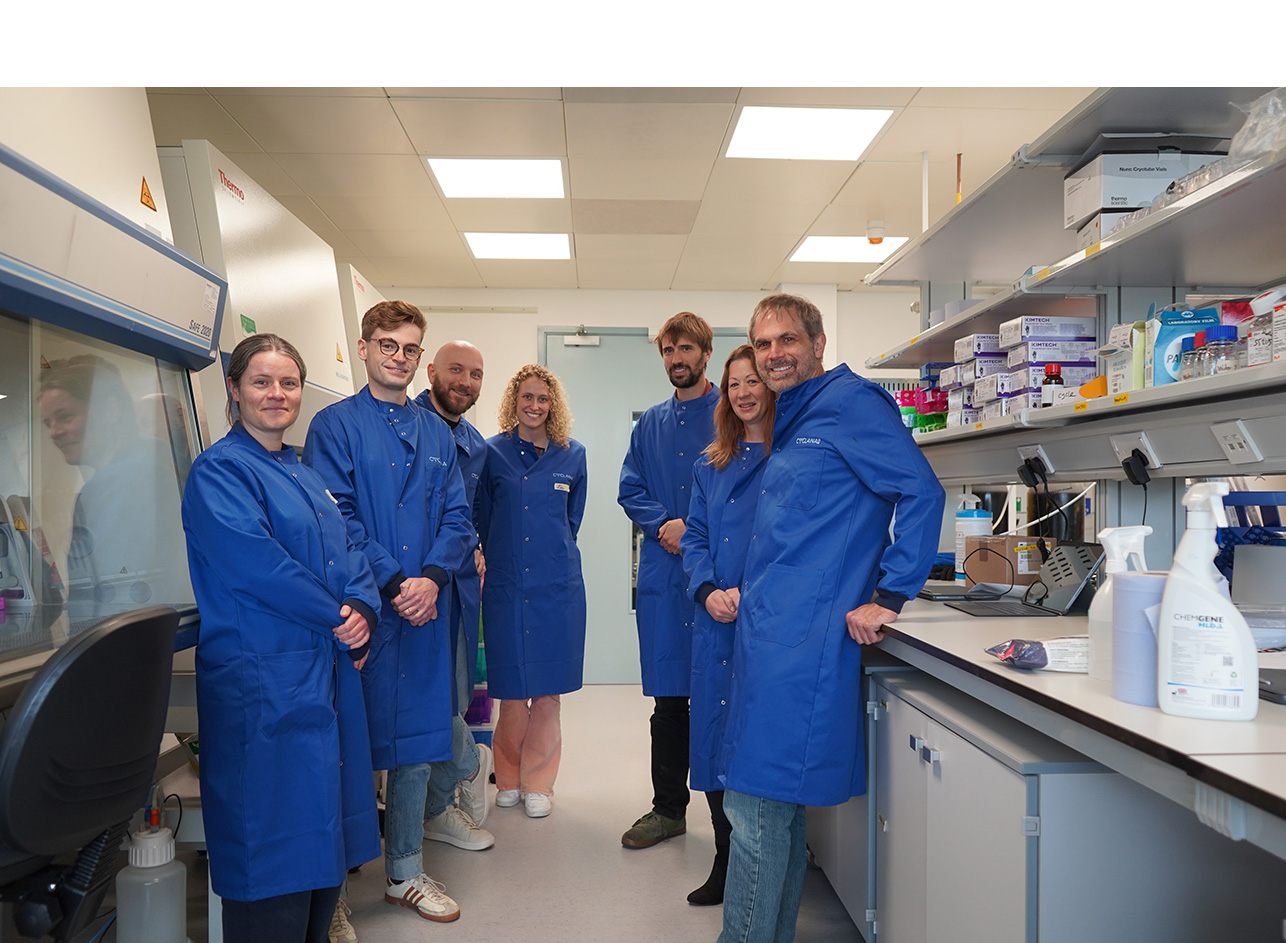
AI is used to bring those layers of data together, looking for drug targets and early biomarkers where the disease begins: in the tissue. Its research points to the extracellular matrix, the scaffolding around cells, as a driver of inflammation in endometriosis, whereas most drug development has focused on pathways inside cells. Using the collected data and cells, they have established an in vitro endometriosis model that captures the dysregulation of this matrix in the disease. With this model they have validated novel targets that can reverse disease behaviours using patient-derived cells and are building a broader therapeutic discovery platform extending to other women’s health conditions and beyond.
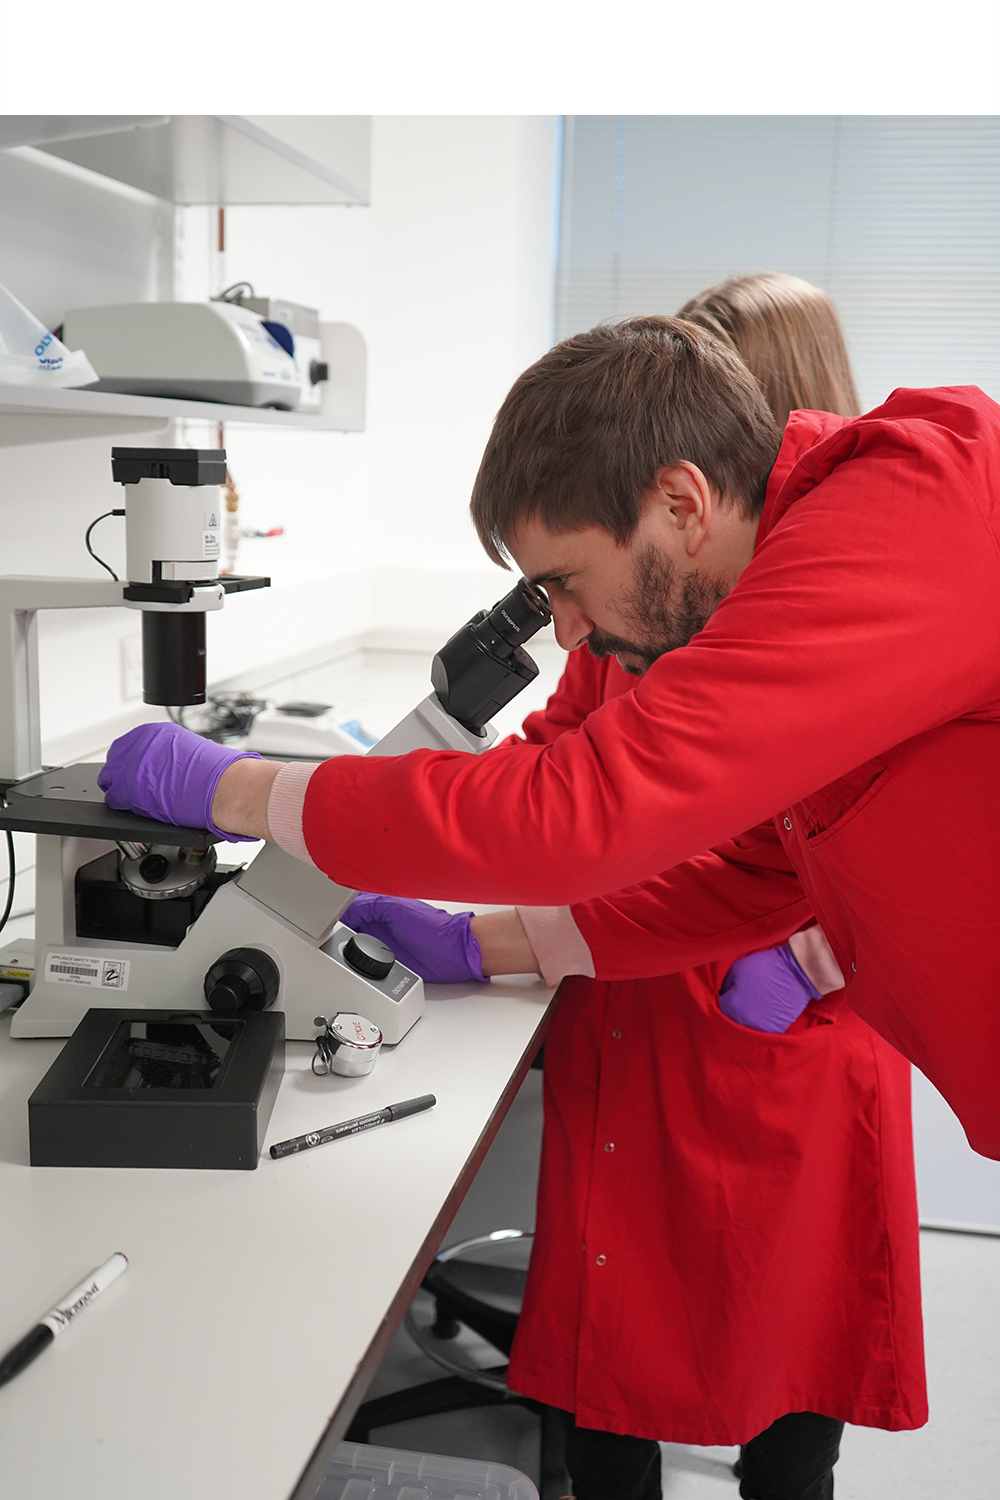
Cyclana is led by CEO Dr Léa Wenger and CSO Professor Kevin Chalut, and closed a £5 million pre-seed round co-led by NFX and Eka in October 2025.
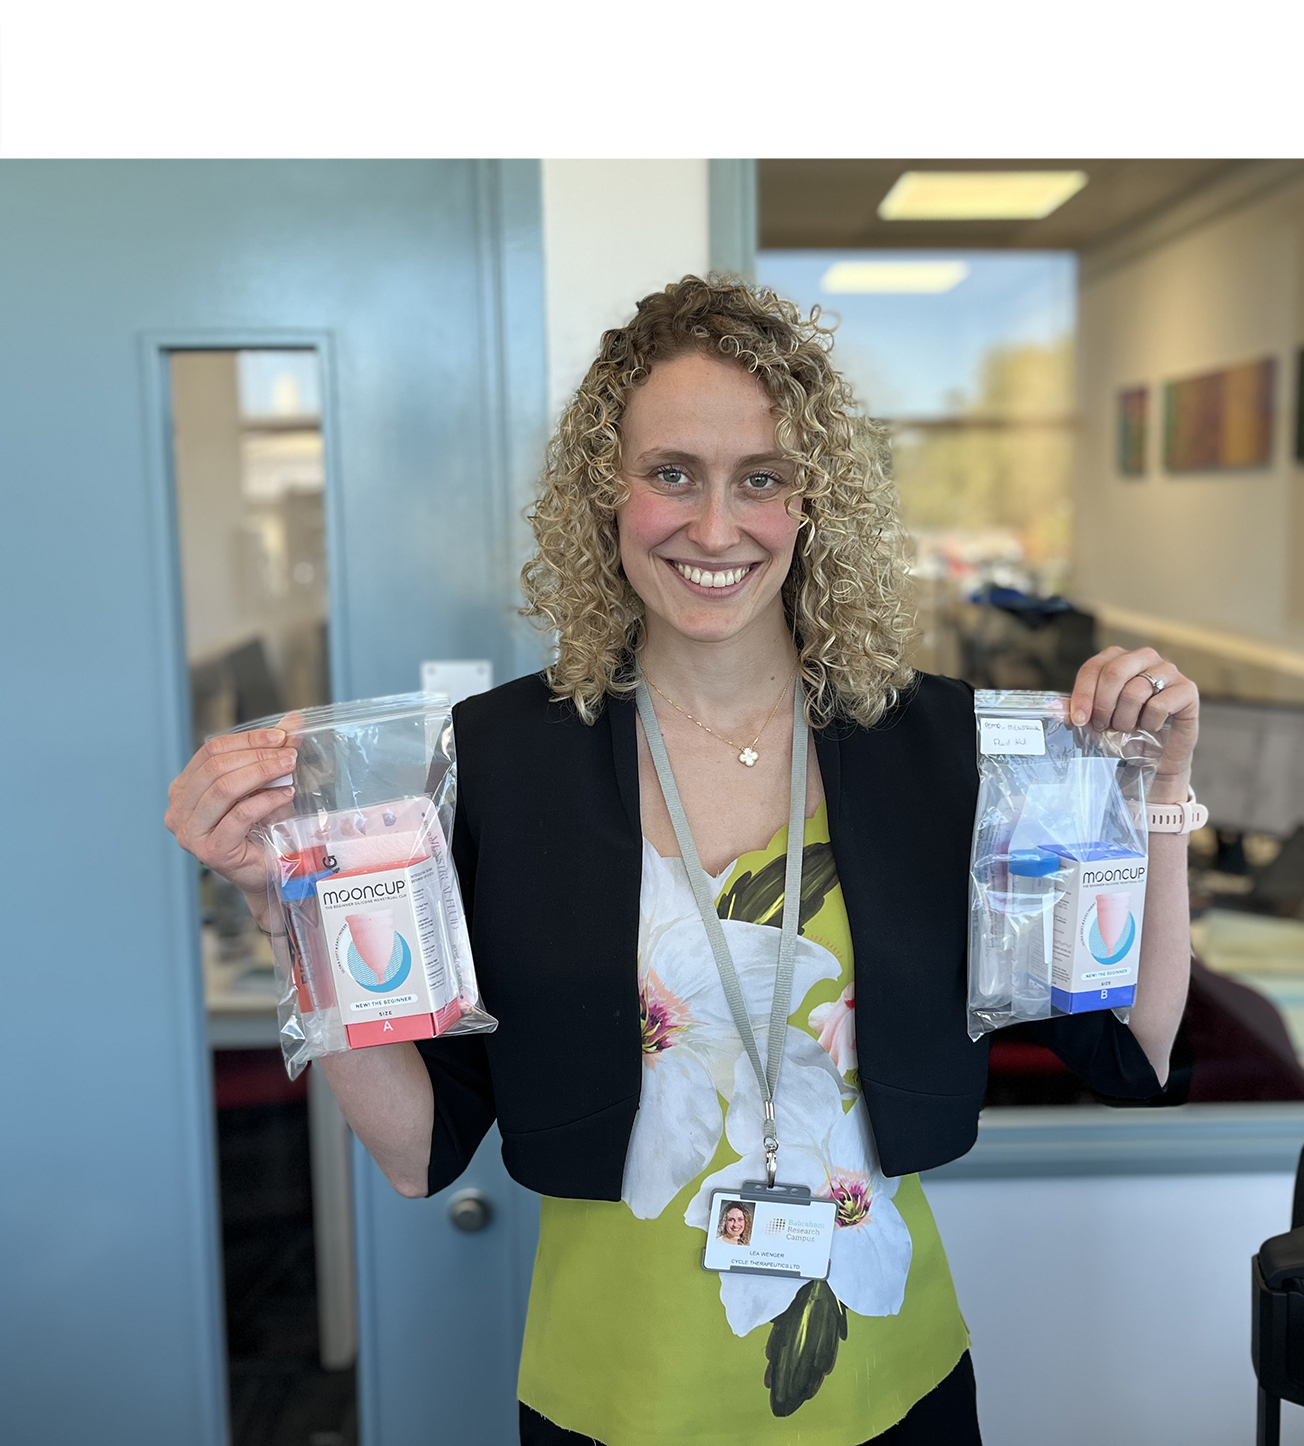
“The uterus is an incredible organ that undergoes processes like scarless regeneration, immune tolerance and beyond. We are leveraging our unique access to this truly human source of health and disease, to understand the basic mechanisms at play. We are excited by the idea of diving deep into women’s health to shed light on the fundamental processes of complex diseases.”
Dr Léa Wenger, CEO and Founder, Cyclana Bio
Case study
Hijack Bio: making the medicine where it’s needed
Insulin and the newer GLP-1 drugs are both peptides, and both depend on a long chain outside the body: manufacture, purification, cold storage, injection. London-based Hijack Bio is asking whether that chain needs to exist.
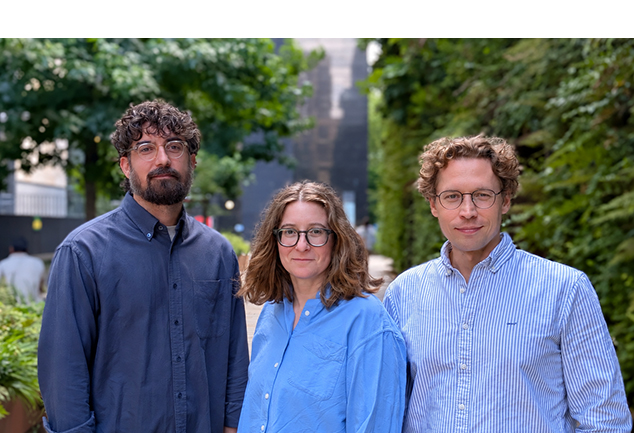
The company is engineering probiotic bacteria to make and release peptide medicines inside the body, removing several layers of manufacturing and delivery. The approach also makes peptide combinations fast to build, which is where the founders see the platform’s edge. Hijack’s first therapeutic programmes are dual oral combinations for diabetes and cardiometabolic disease.
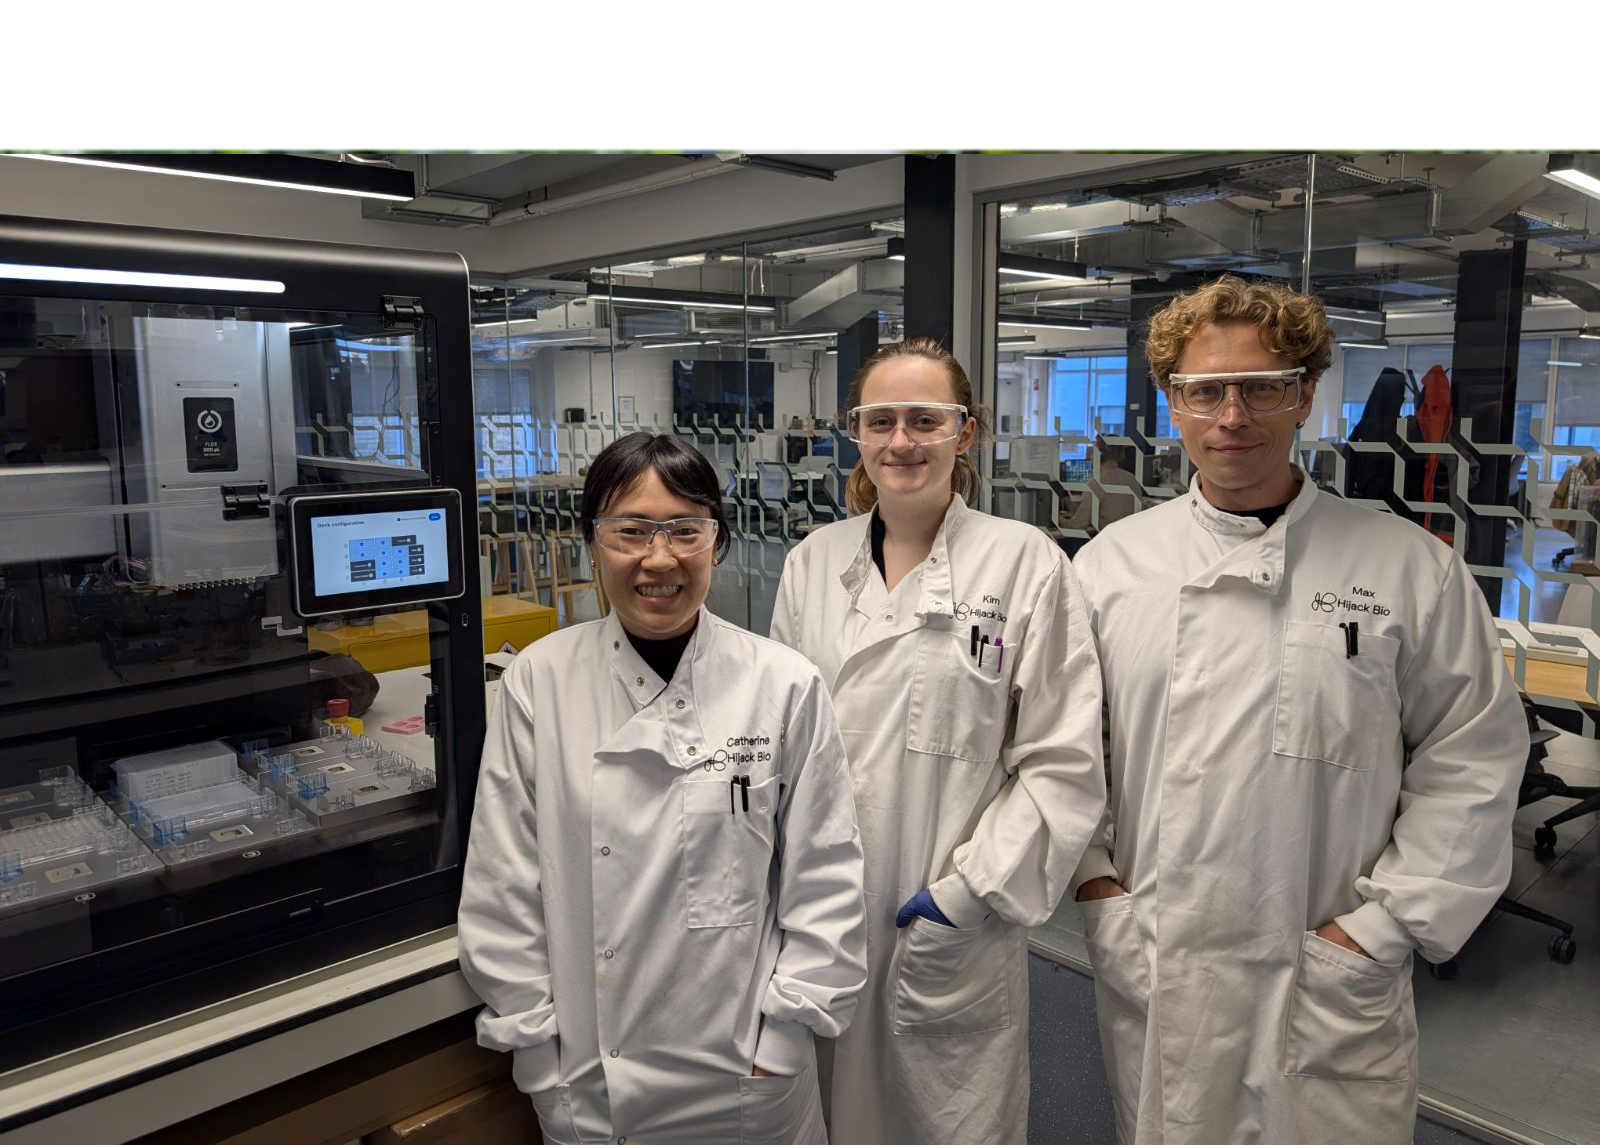
Three founders bring the disciplines together: Salpie Nowinski (CEO), Maximilian Mossner (CTO) and Gabriel Nowinski (CMO), spanning computational biology, molecular biology and clinical medicine, alongside a team split across dry and wet lab. Strain design runs as a closed loop, with machine learning proposing designs and an automated liquid-handling pipeline building and testing them.
Hijack has closed an oversubscribed pre-seed, moved into its own labs last year, and engineered a commensal strain that produces peptides in situ and remains shelf-stable for twelve months. Alongside the science, the team has been working through formulation, manufacturing and regulatory requirements early, taking the view that for a living medicine those questions decide the route as much as the biology does.
“We deliver peptides orally by Hijacking evolutionary pathways that have existed for millennia. This will transform patients’ lives for the better while drastically reducing manufacturing costs. Hijack brings together computational biology, lab automation and a team of exceptional wet lab scientists to bring world-class therapies to as many people as possible. Our mission is to touch a billion lives.”
Salpie Nowinski, CEO, Hijack Bio
 An investor’s view
Think like a drug developer from day one
Diana Roettger
Investment Principal,
LifeArc Ventures
Isomorphic’s round is an impressive achievement, but it isn’t representative of the broader funding environment. It masks how challenging fundraising remains for many TechBio companies.
We’ve seen early-stage technology investors, who initially entered life sciences through the excitement around AI drug discovery, become more cautious about funding novel drug discovery platforms. Instead, some are shifting towards AI applications further downstream in drug development, such as clinical trial design, patient recruitment and trial execution, where the technology can demonstrate commercial value sooner without taking on the full risk and timelines of developing a new therapeutic.
This leaves a funding gap. Traditional life sciences investors tend to focus on therapeutic assets and increasingly expect a clear path to clinical data, while technology investors are becoming less willing to take on drug development risk. As a result, TechBio companies with promising platforms but without validated drug candidates are finding themselves caught between two investor groups.
What has changed over the past year, in my view, is the level of evidence investors expect, and which types of investor are willing to underwrite which technology. We’ve moved beyond the initial excitement about what AI could potentially do in drug discovery, a trend that was largely driven by early-stage technology investors. We increasingly want to see what it can actually deliver.
I don’t think it’s necessarily a question of platform versus pipeline. For me, the most compelling TechBio companies are those where the platform creates a genuine competitive advantage in developing therapeutics.
Ultimately, the largest and most established exits in biotech still tend to be driven by drug assets, particularly those with clinical validation. That’s where we have seen the most significant value creation. However, I think we’re also starting to see another potential route to value, even if exits are likely to be smaller than for drug assets. Across the broader AI industry, large players are acquiring smaller companies for their technology, specialised models, talent and proprietary datasets. I think we could see more of that in TechBio as differentiated biological data and AI capabilities become increasingly strategic.
Pharma partnerships remain an important form of validation and can provide non-dilutive funding, but they don’t necessarily demonstrate that the platform can deliver better medicines. And the economics matter: how much of the downstream value does the company actually retain, and can it re-use what it builds to create a moat?
So I still favour companies that combine a scalable technology platform with the ambition and credibility to develop their own pipeline. That gives you the potential for repeatability and scale, while creating tangible therapeutic assets and retaining more of the upside. For me, the real question isn’t platform or pipeline. It’s whether the platform makes the pipeline fundamentally better, and whether the company can capture the value it creates.
If I could change one thing, I would like to see early-stage TechBio companies engage with traditional life sciences investors much earlier, well before they are actively fundraising. Founders need to understand from the outset what makes a therapeutics company investable, and build their development strategy accordingly.
It’s not enough to have an exciting AI drug discovery platform. Companies need drug development expertise, a credible path to the clinic and a thorough understanding of the competitive landscape, including what conventional biotechs are developing. After all, what’s the value of building an expensive AI and data platform if it ultimately identifies the same targets that other biotechs are already pursuing, without delivering a clear competitive advantage?
My message to TechBio founders is to think like drug developers from day one, not just AI innovators, and to engage with life sciences investors long before you need their capital.
 BIA supporting TechBio innovation
Improving access to health data
Data has always been at the heart of the life sciences sector, informing decisions and advancing innovation from initial discovery through to clinical testing and post-market monitoring. Advances in technology have further accelerated our ability to generate, analyse and derive insights from increasingly large and complex datasets. TechBio is at the forefront of this wave.
For many years, the BIA has championed the needs of the sector in the health data ecosystem, consistently calling for a single front door and a streamlined access process for UK health data that works for innovative UK SMEs.
The Health Data Research Service (HDRS) is a direct response to these priorities. Backed by up to £600 million in funding from the Government and Wellcome, and led by Melanie Ivarsson, HDRS aims to provide a secure, single access point to national-scale health data. By reducing fragmentation and removing barriers that have hindered access for years, the service has the potential to transform the UK’s health data landscape.
The success of HDRS will ultimately be determined by how effectively it meets the needs of UK innovators, particularly the TechBio community. Recognising this, the BIA has been closely involved in shaping the service from its inception. Through roundtables, workshops, stakeholder engagement and active participation in the HDRS Industry Forum, we have consistently championed the interests of start-ups and scaling businesses, ensuring that SME perspectives are embedded within the service’s development and strategic direction.
Earlier this year, we co-hosted a parliamentary health data breakfast with HDRS CEO Melanie Ivarsson, bringing together policymakers and industry leaders to explore the future of health data innovation in the UK. We also facilitated a dedicated roundtable between HDRS and ten BIA member companies, creating a direct channel for industry feedback and helping to inform the design and delivery of the new service.
Our priorities remain consistent. In addition to a single front door and streamlined access process, we are calling for access to rich multimodal datasets, affordable access for UK SMEs, and a harmonised, certified Trusted Research Environment (TRE) model.
Alongside this work, we continue to support major UK health data cohorts to better serve innovators across the life sciences sector. This includes engagement with UK Biobank and Our Future Health, helping these organisations better understand the needs of UK SMEs while also raising awareness of these valuable resources so that more companies can benefit from them.
This work provides the foundation for BIA’s health data vision 2035. Published in May, this landmark report sets out a vision for UK health data as a strategic national asset. It explores global trends in health data and outlines how the UK’s unique strengths can support the Government’s ambitions for preventative and precision medicine.
Endorsed by Kate Bingham and shared widely across government and industry, the report continues to inform policy discussions and shape thinking on the future of UK health data. For example, its recommendations contributed to a new parliamentary briefing on health data and informed the House of Lords Science and Technology Committee’s inquiry into personalised medicine and artificial intelligence.
The BIA vision for health data: a strategic national asset
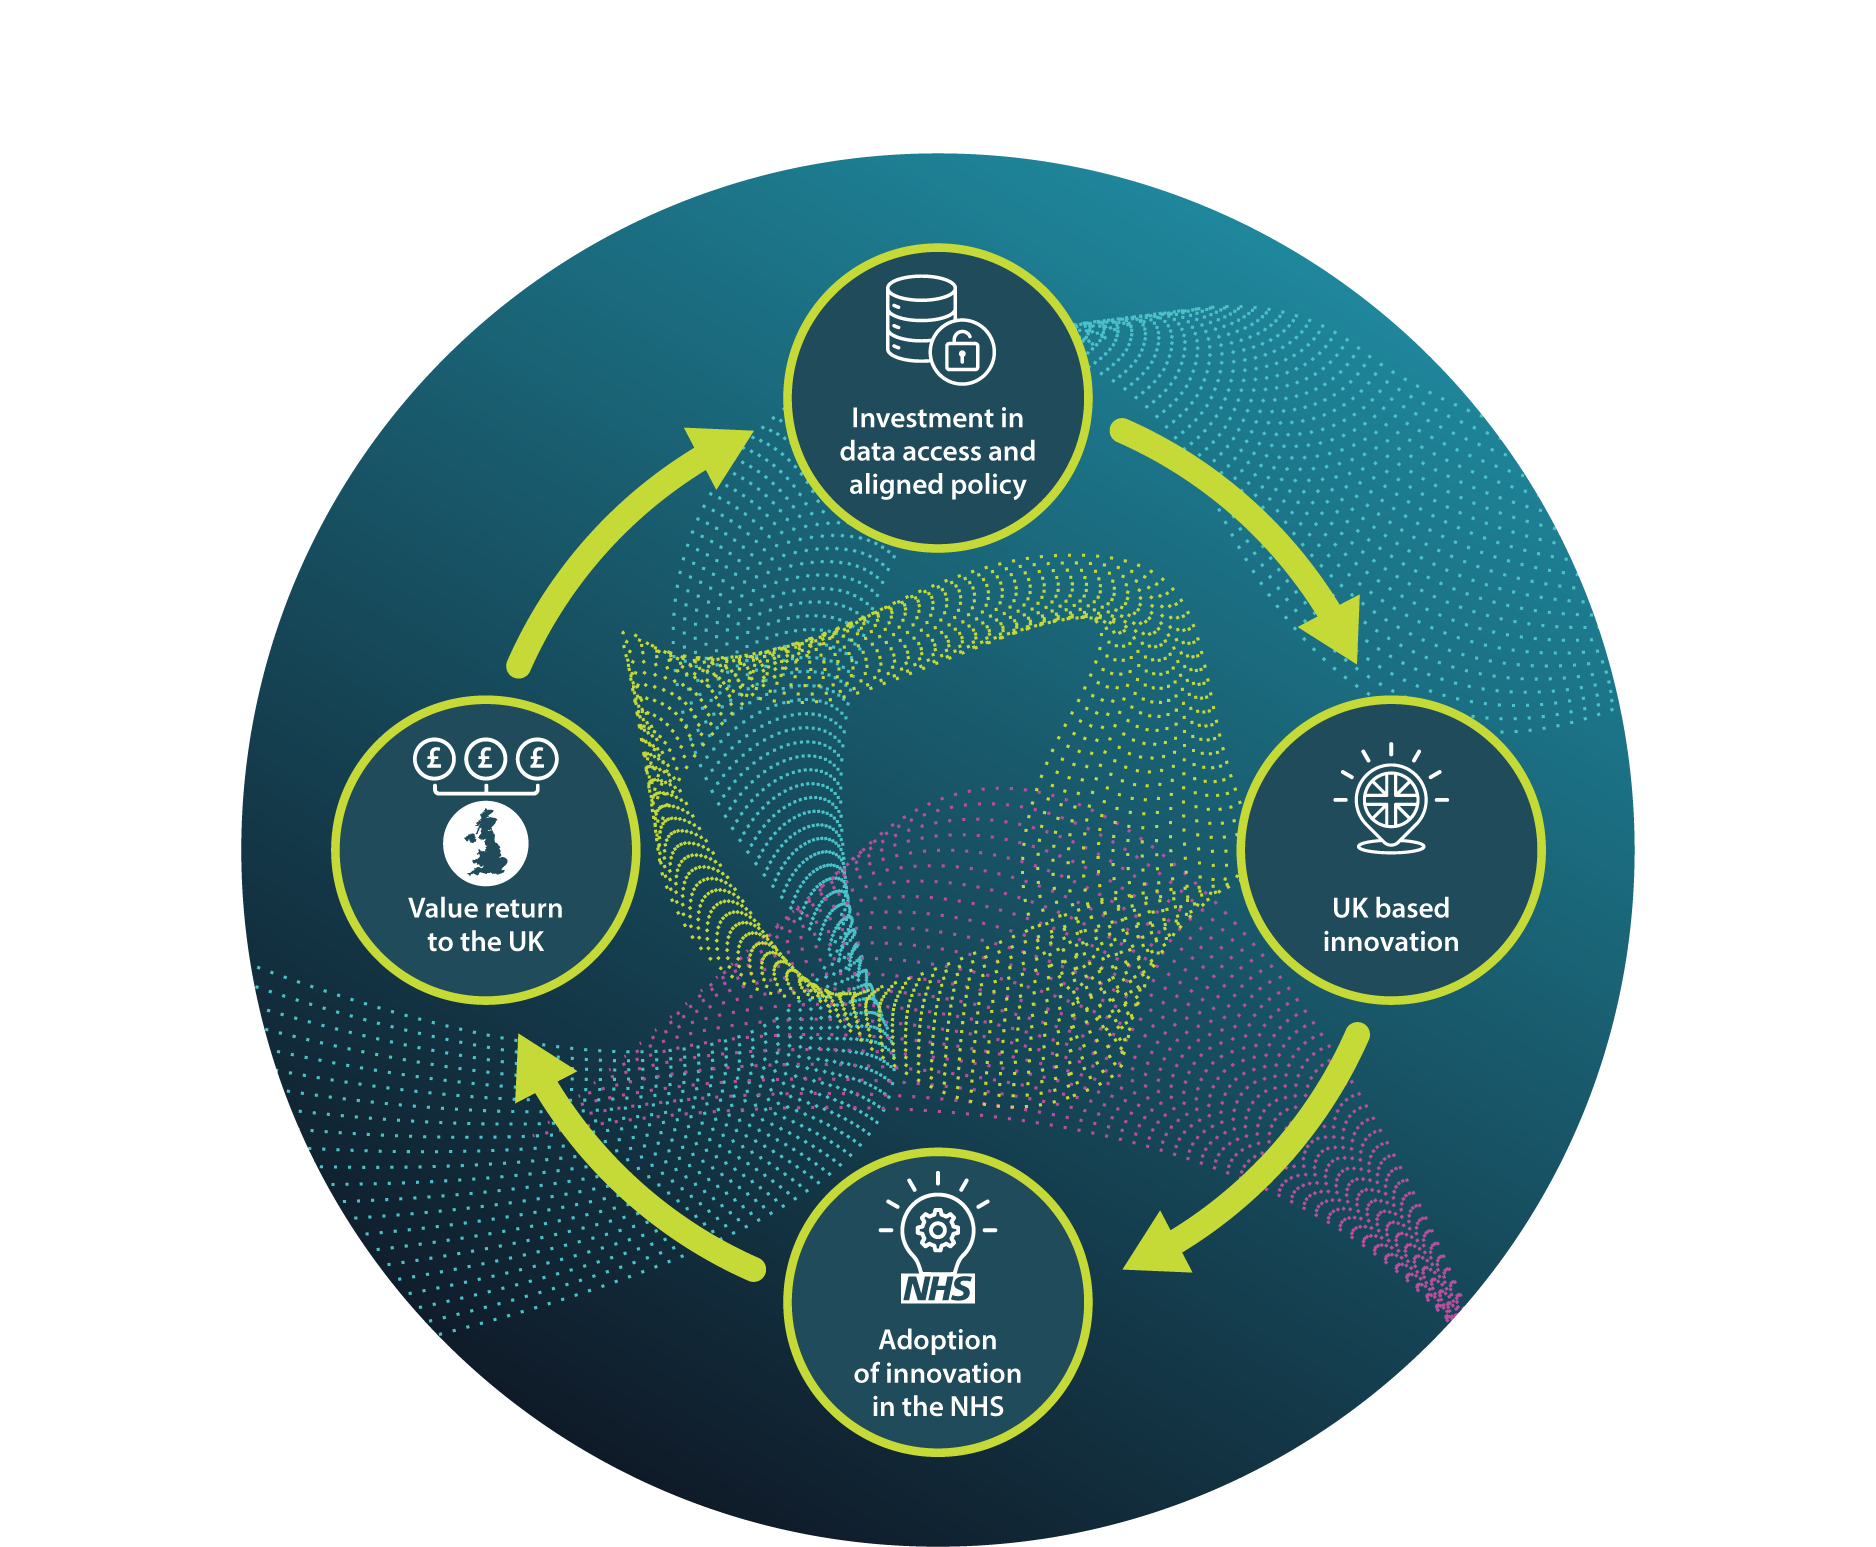
Our vision sets out the need for a deliberate strategy to harness health data as a core national asset to improve health and economic growth.
A trusted, interoperable and accessible health data ecosystem will support innovation, commercialisation and adoption. By doing so, health data can become a strategic national asset that improves patient care, strengthens NHS sustainability, boosts productivity and drives growth in the UK’s life sciences sector. Achieving this will require aligned policies, strong support for UK innovation, secure and ethical data use, and continued public engagement to build trust and demonstrate the benefits for patients, the NHS and the wider economy.
The BIA vision for health data: Five pillars of the health data ecosystem
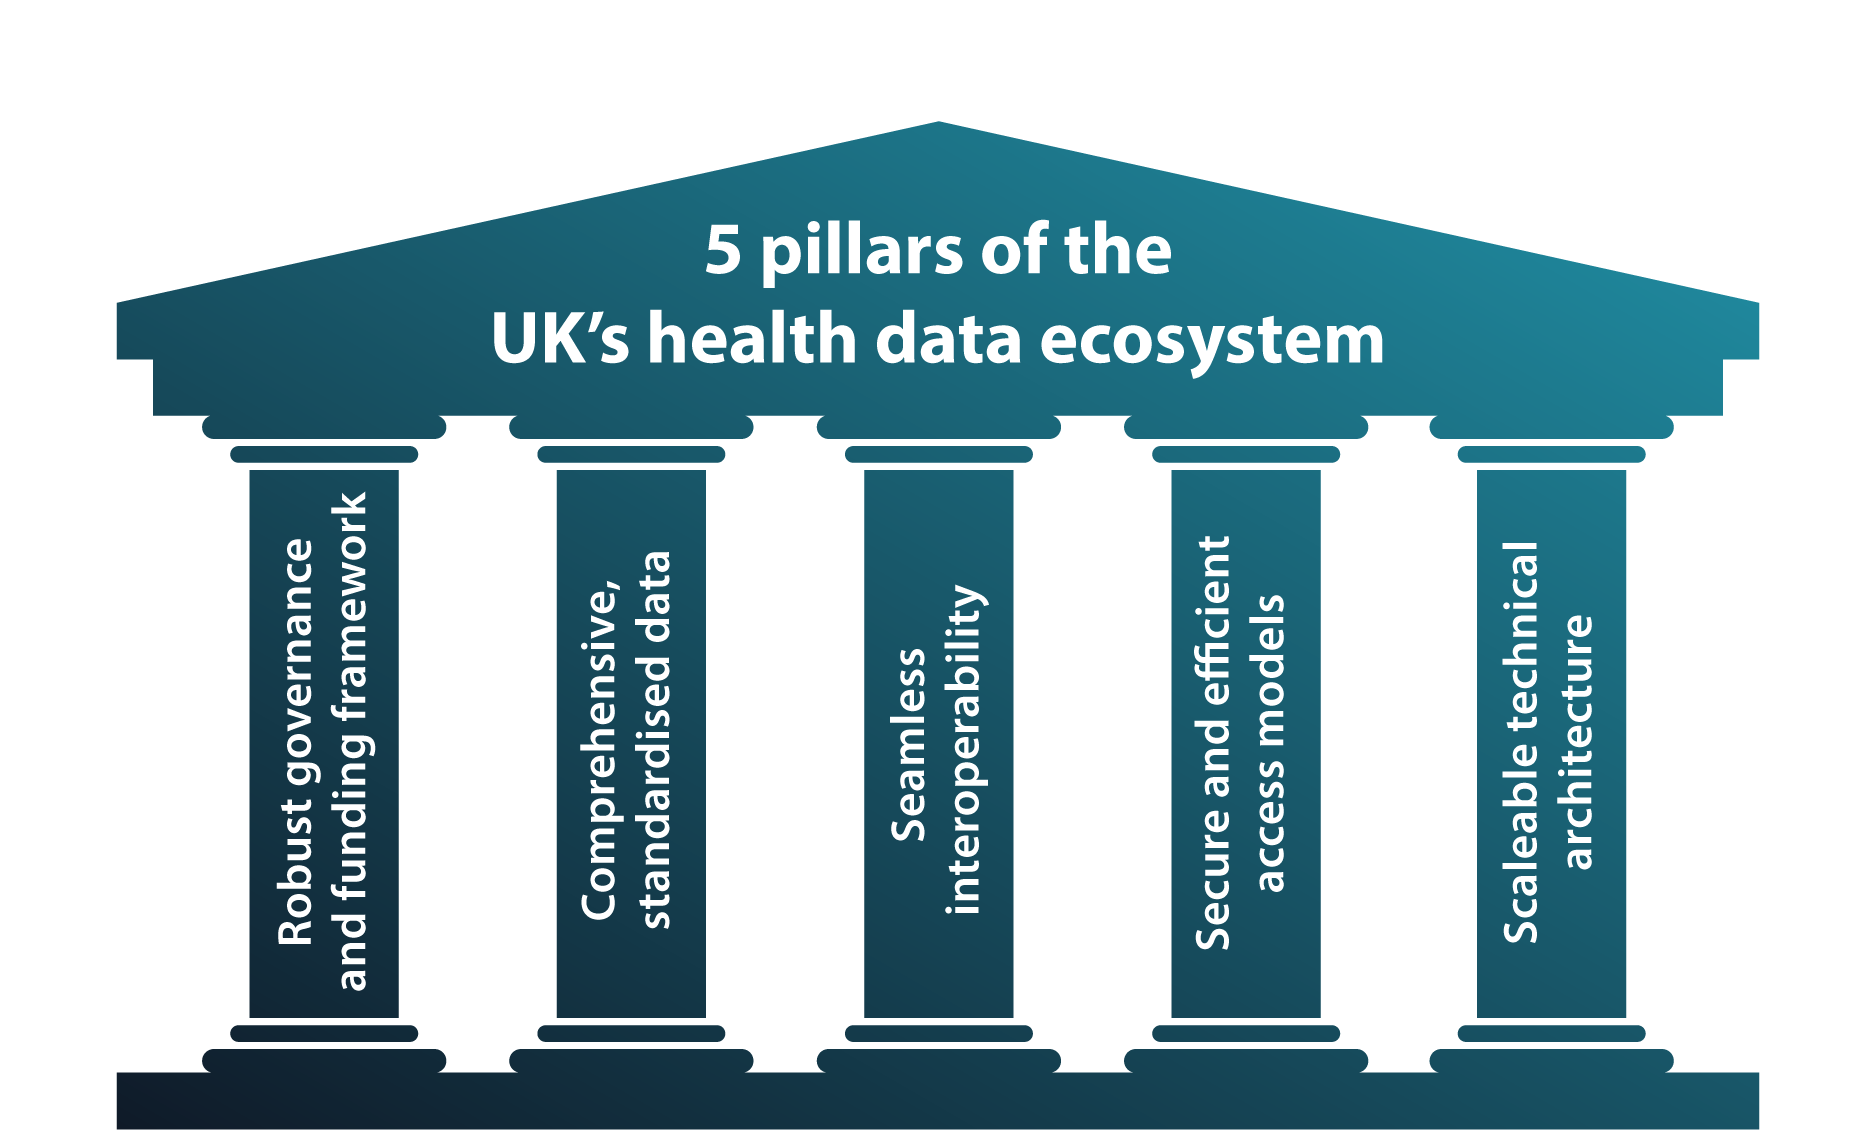
In addition to the landmark vision for data report, we published a paper outlining the technical pillars that will be needed by 2035 to realise this vision. These pillars will support the UK’s health data ecosystem to function as a unified, intelligent platform powering both healthcare and cutting-edge life science innovation.
- A secure and robust governance and funding framework, including affordable access for UK SMEs, free from competing revenue targets, that ensures secure, legally compliant and ethical use, value return to the UK and industry co-development.
A governance framework that provides both strong, effective, protection for patients and is enabling for UK-based innovators – designed to support secure data access while delivering benefits and value to the NHS and its patients at pace.
- Collection and standardisation of comprehensive data including genomics: standardised across longitudinal multimodal sources.
Large-scale integrated clinical and genomic data, including functional genomics, imaging data, unstructured data, wearables and real-world evidence with data quality standards designed to support equitable representation across diverse populations.
- Seamless integration across systems and data types, with up-to-date records and common standards across all four UK nations, supported by defined interoperability standards governance.
Seamless, secure access to diverse, high-quality datasets, alongside governance structures and common data standards.
- Secure and efficient access models that are streamlined and timely, offering different data and access models for different users and applications, underpinned by clear lawful bases for processing and transparent consent and opt-out frameworks.
A modern, flexible and high-performance technical architecture capable of handling large-scale, multimodal health data. This infrastructure will support both care delivery and world-leading research, while reflecting the increasing complexity of real-world data environments.
- Resilient, flexible and scalable technical architecture that is capable of enabling AI and other innovative clinical solutions.
A resilient, future-proof data system will need to support diverse data access and integration models, analytical methods, high-throughput AI workflows and collaborative projects across multiple sectors and geographies.
BIA’s Data, AI and Genomics advisory committee and TechBio community
The BIA’s commitment to building a world-leading TechBio ecosystem has translated into meaningful policy influence and industry leadership. A key part of this work is the Data, AI and Genomics Advisory Committee (DAGAC), launched in September 2024 to help shape the UK’s approach to the rapidly evolving landscape of data-driven life sciences.
Bringing together leading voices from across industry, DAGAC has provided a dedicated forum to identify opportunities, address barriers to innovation and ensure emerging technologies are reflected in policymaking. Through this engagement, the committee has helped strengthen the voice of the TechBio sector and promote a regulatory and business environment that supports innovation, investment and growth. This year’s work included the BIA vision for data and engagement with UK Biobank and HDRS. Beyond data, the BIA also fed into the national commission on regulating AI in healthcare through our representative Dr Michalis Papadakis, chief executive of Brainomix. The Government accepted all 44 of the commission’s recommendations in full in October. By connecting experts across the ecosystem and providing strategic insight to policymakers, the committee is helping ensure the UK remains at the forefront of data, AI and genomics-enabled innovation.
The BIA TechBio community brings together innovators working at the intersection of biology, data science, AI, and technology to accelerate advances in drug discovery, diagnostics, clinical trials and patient care. The community provides a forum for biotech companies, technology experts, investors, and industry leaders to connect, share expertise, and collaborate on common challenges facing the growing TechBio sector. Through networking events, policy engagement, and industry insights the BIA helps strengthen the UK’s position as a global leader in data-driven life sciences innovation.
To learn more and connect with innovators shaping the future of TechBio, join the BIA TechBio community.
Skills
The TechBio community continues to report strong demand for people with skills in AI and machine learning, data analytics and computational biology. These skills underpin the sector’s growth. Through our work with government, the BIA has helped shape the forthcoming Digital and Tech Sector Jobs Plan, so that the needs of the TechBio workforce are reflected in it. The plan sets out workforce needs over the next decade and how government, employers and local partners will open up entry-level routes into digital and tech careers.
The BIA has been named a TechFirst Pathway Champion, helping to deliver the plan and strengthen the talent pipeline for TechBio companies. The plan has four parts: inspiring young people through AI and technology learning, opening entry-level career opportunities at scale, delivering regional priorities with local partners, and sustaining digital and AI skills across the existing workforce.
Our #BIGIMPACT skills programme is also being relaunched. To find out more, join our skills community workshop or sign up to the TechFirst community.
TechBio Boost: A catalyst for growth
TechBio Boost is a programme in collaboration with the Francis Crick Institute to build the leadership of data-driven life science companies looking to scale in the UK. It seeks to enable leaders to overcome key challenges they’re facing, and to attract the necessary talent and resources to develop further. The 2025 cohort included Mendelian, Kiin Bio, Curenetics, AI VIVO and Linkgevity.
 Join the BIA TechBio network
BIA’s TechBio UK and TechBioX events bring the community together — from start-ups and investors to established TechBio companies, big pharma, policymakers, and relevant supporting organisations.
If you’re a TechBio company looking for your tribe, or a biotech, pharma or investor looking to tap into the potential, come along to our events, join the BIA TechBio community, join the BIA TechBio LinkedIn Group, and get in touch about becoming a member.
 Previous reports
TechBio 2025: Future-ready biology
 The TechBio 2025 report from the BIA tracked five years of UK TechBio financing, drawing on our own analysis of 128 companies, and found a sector strong at seed stage but short of later-stage capital. It featured case studies from Ultromics, Genomics, Recursion, SynLaia and Relation, alongside a look at SME access to health data.
The report not only charts the immense potential of the UK’s TechBio sector for economic growth but also grounds our current successes in robust, long-term data and a realism check of the ongoing challenges as it matures.
TechBio in the UK has grown from promise to presence. The next chapter will be about endurance, building the businesses, partnerships and confidence that turn scientific excellence into lasting impact.
Explore five years of UK TechBio financing the companies driving innovation and what SMEs need from health data. Read the TechBio 2025 report.
TechBio 2024: UK leads innovation frontier
 The TechBio 2024 report from the BIA revealed the UK as a global leader in TechBio, drawing substantial investment and nurturing a vibrant ecosystem of talent and businesses. The report documented a growing prevalence of generative AI for designing new drugs and the use of multimodal models that combine different data sources for personalised medicine, highlighting the transformative impact of AI on life sciences. While the report maintained an optimistic tone about the potential for rapid progress, it also focused on crucial policy challenges, including the need for a well-trained workforce and equitable access to high-quality data. The BIA stands resolute in its mission to uplift the TechBio community, advocating for policies that ignite innovation and fuel growth to ensure the sector thrives in the pursuit of groundbreaking advancements in healthcare.
Uncover the latest trends, essential policy challenges, and the transformative impact of UK-based TechBio companies. Read the TechBio 2024 report.
TechBio 2023: UK driving the AI revolution
 The TechBio report offers key insights into how the UK is leading the charge in integrating AI and biotechnology to revolutionise healthcare, drug discovery, and life sciences innovation. This report provides a deep dive into the current trends, opportunities, and challenges facing the TechBio sector, highlighting groundbreaking companies, like Brainomix, CardiaTec, and Serna Bio; emerging technologies, and the UK’s unique ecosystem fostering this growth.
The report also details the BIA’s efforts to address critical challenges such as access to health data for SMEs, nurturing digital talent, securing sustainable investment for scaling companies, and advocating for proportionate regulatory frameworks.
Explore the latest advancements in data sharing, inspiring case studies, and the future of TechBio. Read the TechBio 2023 report.
TechBio 2.0: Unlocking Data, Transforming Biology
 Showcasing the next generation of data-driven life science companies that use cutting-edge technologies to transform drug discovery and patient care.
TechBio companies combine cutting-edge techniques from both sectors to draw insights from a wealth of data, including data concerning patients, drug molecules, healthcare infrastructure and research and development. This data is not only being used to inform and transform drug discovery and patient care but, also addressing challenges faced by industry and agriculture, such as creating cleaner and greener chemicals and materials.
Read the TechBio 2.0 report for developments in data sharing, inspiring case studies and the future of techbio!
TechBio: How data-driven life sciences companies are transforming drug discovery and patient care
 This explainer booklet gives an introduction to the exciting BIA member companies that are working at the interface of biotechnology and technology, and shows how they are already making an impact on drug discovery and patient care. Data-driven life sciences technology or tech bio is an area where the BIA is rapidly building its expertise and we will be working hard to bring together all elements of the biotechnology landscape to ensure that these companies have the right policy framework and the investment that they need to grow and succeed.
Please download the full TechBio report for case studies of incredible companies working at the interface of biotechnology and technology.